
Two forecasters face the same economy. One looks at last year’s inflation and nudges last year’s guess toward it. The other works out what the central bank’s rule implies and forecasts that. In the intermediate macro sequence at the University of Chicago and Northwestern, and at Loyola, DePaul and UIC, the second forecaster is where the Phillips curve chapter turns difficult, because once people reason about policy, the estimated relationships that policy relied on stop holding. This Lucas critique lesson from a Chicago macroeconomics tutor puts both forecasters inside one model, runs the same policy change through each, and shows exactly which regression breaks and why. Sessions are one-on-one, built around your own problem sets.
One supply curve, two ways to fill in the forecast
Start with the supply side written in terms of surprises. Let xt be the output gap in year t, in percent of potential, πt the inflation rate and πet the inflation people expected for year t when they set wages and prices at the end of year t − 1:
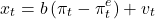
This is the expectations-augmented Phillips curve rearranged, and it is also the Lucas supply curve. Output rises above potential only when inflation comes in above what was built into contracts. Anticipated inflation changes nothing real. The parameter b says how much output a one-point surprise buys, and vt collects supply shocks. Take b = 0.5 in the worked example: a surprise of one point raises output half a percent above potential.
Everything else in the chapter comes from what you write in place of πet. The equation is not the model. The forecast rule is.
Model one: adaptive expectations, a rule for revising a guess
The adaptive forecaster keeps a running estimate and moves it toward the last observation by a fixed fraction λ:
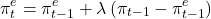
With λ = 1 the forecast is last year’s inflation. With λ = 0.5 it moves halfway. Substitute backward and the forecast is a weighted average of the whole past, with weights λ, λ(1 − λ), λ(1 − λ)2 and so on. Recent years count most, but nothing except past inflation ever enters. A speech, a new governor, a published rule: none of it moves the forecast until it shows up in the data.
That rule has one property that decides everything below. When inflation moves permanently, the adaptive forecaster is wrong in the same direction year after year. If trend inflation rises from 2 to 6 and λ = 0.5, the forecast errors run 4, 2, 1, 0.5, 0.25. Every one is positive. A forecaster who could see the pattern in their own mistakes would fix the rule. The adaptive forecaster, by construction, never does.
Model two: rational expectations, the forecast the rule implies
Muth (1961) proposed the alternative in a paper on commodity prices: let the forecast inside the model be the forecast the model itself produces. Expected inflation is the mathematical expectation of actual inflation given everything known at the end of year t − 1, including the policy rule:
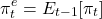
This does not mean people are never wrong. It means their errors are unpredictable from what they knew. If the central bank sets inflation by the rule πt = μ + εt, where ε is a serially uncorrelated shock with mean zero, then the rational forecast is μ, the error is εt, and no error is correlated with any earlier one. The forecast is a function of the rule. Change μ, and as soon as the change is known the forecast changes with it.
Put that forecast into the supply curve and the systematic part of policy drops out:
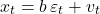
Output depends only on the policy surprise and the supply shock. This is the policy-ineffectiveness result of Sargent and Wallace (1975). It does not say monetary policy does nothing: unanticipated policy still moves output, and the result needs prices free to adjust every period. Add multi-year contracts and anticipated policy matters again. But the step that produced it, the forecast being a function of the rule, is general, and it is the step that matters next.
Raising trend inflation from 2 to 6: the same change, three outcomes
The central bank has held trend inflation at 2 percent for long enough that both forecasters expect 2. At the start of year 1 it moves to 6 and stays there. Set the shocks to zero so you can see the mechanics. The adaptive forecaster has λ = 0.5.
| Year | Adaptive forecast | Surprise | Gap, adaptive | Gap, rational, move unannounced | Gap, rational, move announced |
|---|---|---|---|---|---|
| 1 | 2 | 4 | 2 | 2 | 0 |
| 2 | 4 | 2 | 1 | 0 | 0 |
| 3 | 5 | 1 | 0.5 | 0 | 0 |
| 4 | 5.5 | 0.5 | 0.25 | 0 | 0 |
| 5 | 5.75 | 0.25 | 0.125 | 0 | 0 |
| Total, all future years (infinite sum) | 4 | 2 | 0 |
Under adaptive expectations the gap starts at b × 4 = 2 and halves each year. The surprises form a geometric series, so the total gain over all future years is bΔ/λ, where Δ is the size of the move: 0.5 × 4 / 0.5 = 4 percent-years of extra output. The first five years deliver 3.875 of it. Smaller λ means slower learning and a bigger total: the slower people learn, the more a surprise is worth.
Under rational expectations the answer depends on one fact the adaptive model cannot even express: whether the move was announced. If the bank raised μ without warning, year 1 is a genuine surprise and the gap is 2. Once the new rule is known, which the no-shock table assumes happens after one year, the gap is zero for good. The total is 2. If the bank announced the change in advance and was believed, expected inflation jumped to 6 in year 1 along with actual inflation. No surprise, no output, total zero. Inflation went up for nothing.
The comparison is not about which model fits the data better. It shows that the same policy has different effects depending on how forecasts are formed, so any estimate of “the effect of policy” has the forecast rule baked into it. That is the critique.
The regression that looked structural
Lucas (1976) made the point about estimated equations rather than about any one model. Suppose the rational-expectations economy has lived for thirty years under the rule πt = 2 + εt. A policymaker regresses the output gap on inflation and finds a clean positive relationship. In a simulated run with b = 0.5, inflation shocks of standard deviation 1.2 and supply shocks of 0.3, the fitted line is
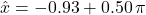
The slope is right: within a regime, higher inflation means a bigger surprise, which means more output. The policymaker reads the equation as a menu. Raising trend inflation to 6 should deliver a gap of −0.93 + 0.50 × 6 = +2.07 percent, permanently. So the rule is changed to πt = 6 + εt, and the economy runs another thirty years.
The second cloud sits to the right of the first, at inflation near 6.0, and at the same height: its average gap is −0.05. Refitted on the new regime, the line is x̂ = −3.40 + 0.56π, a similar slope and an intercept about two and a half lower; the population values are −1 and −3, so the shift is really −2 and the rest is sampling error. Nothing about the supply curve changed. The intercept moved because it was never a structural constant. Substitute the rational forecast into the supply curve and the fitted relationship is really
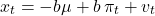
The intercept is −bμ, a function of the policy parameter. The regression was stable only for as long as μ was. The moment policy used the equation, the equation moved. The estimated slope survived; the estimated constant, which is what the prediction leaned on, did not.
The same experiment in the adaptive economy tells you where the critique bites and where it does not. Fit the supply curve with the surprise on the right, x on (π − πe), using the adaptive forecast rule with the true λ, and the regime-1 estimate is x̂ = 0.08 + 0.53(π − πe). Used to predict the second regime it misses by 0.14 on average. The inflation-only regression fitted in the same economy misses by 2.17, fifteen times as much. So the problem is not rational expectations as such. It is any estimated equation whose coefficients quietly absorb a forecast, and under rational expectations every forecast is a function of the policy rule.
Lucas’s conclusion was about method. The coefficients of a consumption function, an investment equation or a Phillips curve mix stable taste and technology parameters with decision rules, and decision rules depend on what agents expect policy to do. Policy evaluation needs the deep parameters, here b, taken as structural, and the shock variances, plus a model of how expectations respond to the rule being evaluated. A regression through the old regime, read as a menu, skips both.
When each model is the right one
Rational expectations wins the policy-change question. If you are asked what a credible, announced disinflation costs, or why a central bank spends so much effort on credibility and independence, the adaptive model has nothing to say, because it cannot represent an announcement. The ends of the great European inflations of the 1920s, in which price stability returned within months of a credible fiscal and monetary reform, are the standard evidence that expectations can move all at once; Sargent’s 1982 account is the usual reference.
Adaptive expectations win when regimes are stable and information is costly. Inside a regime that has not changed for years, the two forecasts of trend inflation converge on the same average, and the adaptive rule is a fair description of a household that does not read central bank minutes. Learning models, in which agents run their own regressions and update as data arrive, sit between the two and often converge to the rational-expectations equilibrium. So rational expectations is the right default for any question involving a change in the rule, and the adaptive model is a tractable approximation for questions that do not.
Two cautions for exam answers. Rational expectations is not perfect foresight: errors occur every period, and in the figure above they are large. And the critique is about parameters, not a claim that econometrics is useless. A regression estimated on one policy regime describes that regime well. The error is using it to forecast a different one.
Three problems with worked answers
Problem 1. b = 0.8 and the adaptive weight is λ = 0.25. Trend inflation rises permanently from 3 to 6 at the start of year 1, with no shocks. Find the output gap in each of the first three years, the forecast at the start of year 3, and the total gain over all future years.
Answer. Year 1: the forecast is still 3, the surprise is 3, the gap is 0.8 × 3 = 2.4. Year 2: the forecast moves a quarter of the way, to 3.75, the surprise is 2.25, the gap is 1.8. Year 3: the forecast is 3.75 + 0.25 × 2.25 = 4.3125, the surprise is 1.6875, the gap is 1.35. Three-year total 5.55. All future years: bΔ/λ = 0.8 × 3 / 0.25 = 9.6 percent-years.
Problem 2. An economy with b = 0.6 and rational expectations has run for years under trend inflation μ = 3. Write down the regression line of the gap on inflation that a long sample would produce. A policymaker uses it to predict the effect of moving to μ = 5. Ignoring shocks, what does the equation predict, what happens if the move is announced and believed, and what would happen in a naive-expectations economy where the forecast is last year’s inflation?
Answer. The population line is x = −bμ + bπ = −1.8 + 0.6π. At π = 5 it predicts a gap of −1.8 + 3.0 = +1.2. Under rational expectations with the move announced, the forecast is 5 in the first year of the new regime, the surprise is zero and the gap is zero. In the naive economy the first year’s forecast is 3, so the gap is 0.6 × 2 = 1.2, and from the second year it is zero. The equation’s “permanent” 1.2 turns out to be one year’s worth.
Problem 3. The central bank now responds to last year’s gap: πt = 2 + 0.5 xt−1 + εt, and the rule is public. Last year’s gap was 2 and last year’s inflation was 2. This year’s shock is ε = 1 and b = 0.5. Find the gap under rational expectations and under naive expectations. Then repeat with no shock.
Answer. The systematic part of the rule is known at the end of last year: 2 + 0.5 × 2 = 3, which is the rational forecast. Actual inflation is 3 + 1 = 4. Rational: the surprise is 1 and the gap is 0.5. Naive: the forecast is last year’s 2, the surprise is 2 and the gap is 1. With no shock, inflation is 3: the rational gap is zero, because the feedback was fully anticipated, while the naive gap is 0.5 × (3 − 2) = 0.5. The feedback coefficient does nothing to output under rational expectations and something under naive ones.
If this is the week your course moves from the Phillips curve to rational expectations, the fastest way through it is to work your own problem sets with a macro tutor in Chicago hours. One-on-one macroeconomics tutoring for UChicago and Northwestern students, and for Loyola, DePaul and UIC, goes line by line through the forecast rule, the substitution and the regression, until the critique is something you can reproduce rather than recite.
A Chicago macroeconomics tutor for the expectations chapter and beyond
Send the problem set, the lecture notes or the past exam that is giving you trouble. A PhD tutor in macroeconomics will set up sessions online at times that fit a Chicago timetable, working from your course’s own notation. Use the WhatsApp button at the top of the page, or book through the form, and say which course you are in.
